UK businesses should prepare their finance software to exchange structured invoice data, while avoiding replacement decisions based on an assumed final specification. The government has announced mandatory e-invoicing for all VAT invoices from 2029. For small and mid-sized firms, the practical work is checking data quality, connections and support responsibilities. The evidence reviewed does not establish the final UK technical specification, so software commitments need checking against published requirements as they develop.
What changes inside a UK finance team
The useful distinction is between sending an invoice that someone can read and exchanging data that another finance system can process. The government’s consultation response centres on the latter, including exchange between different financial systems.
For an enterprise resource planning system, or ERP, the preparation question is therefore more specific than “Can it email an invoice?” Ask whether invoice fields can leave the system in a supported structure, reach the intended customer and return meaningful delivery or rejection information.
Consider an illustrative British wholesaler whose finance staff retype supplier invoices. Its pilot should test whether an incoming invoice matches the supplier record, purchase order and goods received. A successful transmission should not be treated as permission to pay an incorrect invoice.
Faster handling is a plausible benefit, but it is not a guaranteed saving for every business. In its consultation launch announcement, the government reported an NHS trust example where electronic invoices were ready for processing within 24 hours, compared with 10 days for paper invoices. That example concerns processing readiness, not a universal payment deadline.
What is established and what remains unresolved
The strongest primary evidence supplied establishes the government’s intention to mandate e-invoicing for all VAT invoices from 2029 and to develop the regime with stakeholders. It does not provide a final technical implementation specification. The consultation response is the appropriate starting point for that distinction.
Later reporting by RTC Suite describes Peppol as the confirmed core network, while describing the precise document standard as still being finalised. The underlying June government announcement is not reproduced in the supplied evidence, and secondary accounts disagree about how settled the document specification is.
For procurement, separate three questions:
- Data requirements determine which invoice fields and validation rules the software must support.
- Transmission requirements determine how invoices reach another organisation.
- Operational requirements determine how staff identify failures, correct records and maintain evidence of what happened.
A supplier’s general statement that it supports Peppol does not, by itself, demonstrate support for every eventual UK requirement. Request the exact supported specification, UK release commitment and test evidence before treating a proposal as compliant.
UK obligations and existing public contracts
The announced economy-wide policy and existing public procurement rules are separate matters. The Cabinet Office guidance, updated on 20 July 2026, explains that section 67 of the Procurement Act 2023 implies a term requiring contracting authorities to accept and process undisputed invoices in the required electronic form.
That is not evidence that every UK business must already send every invoice through Peppol. Nor should a requirement applying to a particular public contract be assumed to settle the future rules for all VAT invoices.
If you supply a public body, establish the applicable procurement regime and contractual requirements with that buyer, including the relevant UK jurisdiction. For the future mandate, seek the published implementation rules before fixing assumptions about exemptions, exact commencement dates or additional reporting duties.
This is not legal advice; consult your legal counsel.
How ERP connections should be assessed
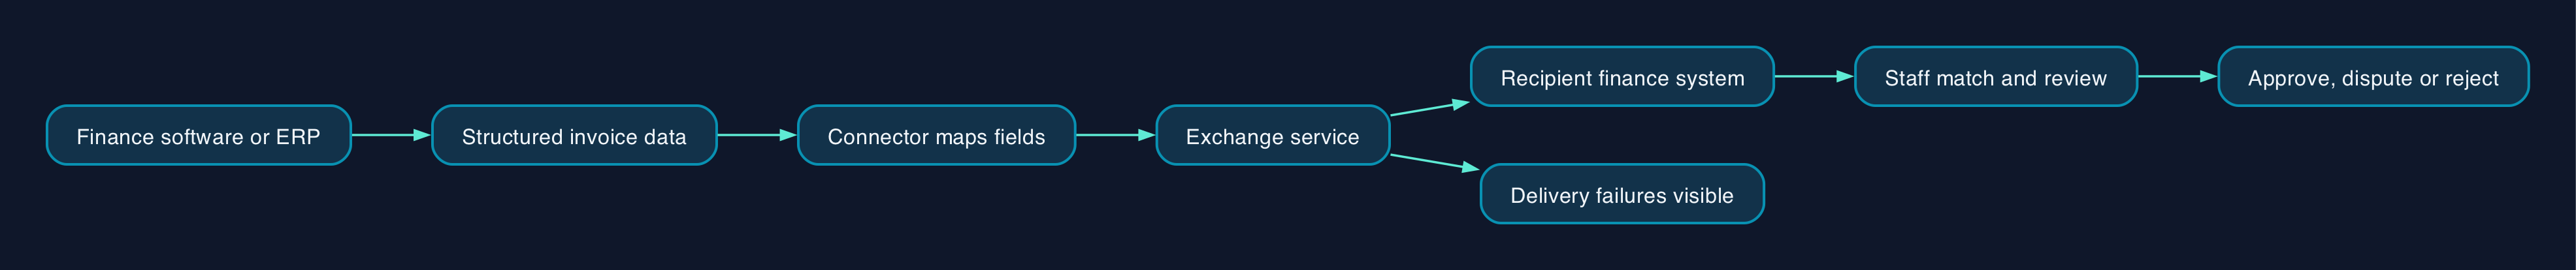
Treat the connection as an operational service with named owners. The following is an illustrative responsibility model for evaluating proposals, not a prescribed UK architecture.
| Component | What the pilot should demonstrate | Suggested accountable owner |
|---|---|---|
| Finance software or ERP | Invoice totals, tax treatment and customer or supplier details export accurately | Finance lead |
| Connector or conversion service | Source fields map correctly and invalid records produce understandable errors | Software supplier or integration partner |
| Exchange service | The intended recipient receives the document and delivery failures become visible | Contracted service provider |
| Receiving finance process | Staff can match, approve, dispute or reject the invoice appropriately | Accounts payable lead |
| Monitoring and records | Staff can trace failures, reconcile transactions and retrieve records | Finance systems owner |
Test both sending and receiving where relevant to the business. Include credit notes, duplicate submissions, incorrect customer identifiers and temporary service failures.
Ask the provider to distinguish technical delivery from business acceptance. Your finance team needs to know whether an invoice reached a system, passed validation or was approved for payment.
Pricing and the full cost of connection
There is no defensible market-wide compliance price in the supplied evidence. One concrete reference is KICK ICT’s Electronic Invoice Processing listing, which publishes £200 to £500 per licence per month.
Those are the lower and upper bounds of one G-Cloud 14 listing, not competing quotations or a typical small-business price. The extract reviewed on 28 September 2026 does not establish VAT treatment, minimum quantities, billing commitment or which configuration attracts each price.
| Cost component | Evidence or quotation requirement |
|---|---|
| Recurring licence | The cited listing publishes £200 to £500 per licence per month. Confirm the applicable configuration and contract terms. |
| Infrastructure | The listing requires a customer-supplied Microsoft SQL Server database. Establish associated hosting, licensing and administration costs. |
| Implementation | Request a separate scope for field mapping, configuration, testing and deployment. |
| Support | The listing identifies additional charges for weekend and onsite support. Confirm incident response commitments. |
| Internal work | Budget finance staff time for data correction, testing, training and exception handling. |
| Exit | Obtain the format, assistance charges and timetable for extracting records and changing providers. |
Compare proposals over the same contract period and invoice workload. Include recurring fees, implementation, infrastructure, staff time, support and exit. A low subscription is not a complete total cost of ownership calculation.
Which software and service route fits
Start with the system you already operate. Replacement becomes a credible option when a supported connection cannot meet your requirements, or when broader finance problems already justify migration.
The evidence does not support a feature ranking of Sage, Xero or other accounting platforms against the eventual UK specification. The comparison below therefore distinguishes practical routes and the evidence each needs.
| Route | When to investigate it | What to establish before committing |
|---|---|---|
| Retain existing accounting software, including Sage or Xero where already used | Current accounting workflows meet the business’s needs | Exact UK edition support, sending and receiving coverage, release date, fees and partner dependencies |
| Add an invoice-processing service such as KICK ICT EIP | Invoice handling is the main problem and the ERP remains useful | Its listing describes business rules, account coding and a Peppol access point; verify compatibility with your ERP and future UK requirements |
| Assess a specialist connection provider such as Open ECX | Several invoice sources or established ERP workflows need connecting | Its own description discusses inbound conversion and system integration; require a demonstration using your records and written responsibility boundaries |
| Replace the finance platform | Existing limitations extend beyond invoice exchange | Compare migration, reporting, training and exit costs alongside the proposed connection |
The named service capabilities come from KICK ICT’s published service record and Open ECX’s own description. These are supplier statements, not independent evidence of delivery quality or final UK compliance.
For a small firm, a supported update to its existing package is a sensible first enquiry. A mid-sized business with several entities should also test whether one service can handle their different systems without hiding failures from local finance teams.
Editorial analysis
The most useful preparation is to expose weak invoice data and unclear ownership before signing a migration contract. A connection cannot resolve a disputed purchase order simply by transmitting it successfully.
Ask shortlisted suppliers to demonstrate an invoice leaving your system, entering a different buyer’s system and returning an actionable failure when something is wrong. Make responsibility for specification changes, connector maintenance and incident resolution explicit in the proposal. That demonstration is more useful than a general promise of readiness.
Sources
Dates below are those shown in the supplied evidence. Extracts were reviewed on 28 September 2026.
- HMRC and Department for Business and Trade consultation response on electronic invoicing, updated 26 November 2025.
- HMRC and Department for Business and Trade announcement of the e-invoicing consultation, published 13 February 2025.
- Cabinet Office guidance on electronic invoicing and payment, updated 20 July 2026.
- Digital Marketplace listing for KICK ICT Electronic Invoice Processing, publication date not shown in the supplied extract.
- RTC Suite account of the UK Peppol network announcement, dated 25 June 2026 in the evidence record.
- Open ECX preparation guide for the UK e-invoicing mandate, dated 30 July 2026 in the evidence record.