For a UK subscription box, membership or SaaS business billing customers monthly, GoCardless's Direct Debit is usually the cheaper rail once revenue per customer rises above a few pounds, because its fee caps at £4 regardless of the charge and bank pulls fail far less often than cards. Stripe Billing and Chargebee both add a recurring-billing surcharge on top of card processing, and their published payment-recovery figures come from case studies rather than one audited average, so treat any single recovery-rate claim with caution and check it against your own failure mix.
Key pointers
- GoCardless charges 1% plus 20p per UK Direct Debit, capped at £4, with no monthly fee on its Standard plan; the cap makes it materially cheaper than card billing above roughly £15 to £20 a charge.
- Stripe Billing adds a 0.7% fee on top of Stripe's card rate (1.5% plus 20p for UK cards), so a £30 monthly charge costs about 36p more through Stripe than through GoCardless.
- Chargebee is not a payment processor. Its new Flow plan charges 0.80% of billing value (or 0.65% plus $99 a month on a commit plan) on top of whatever gateway, such as Stripe or GoCardless, actually moves the money.
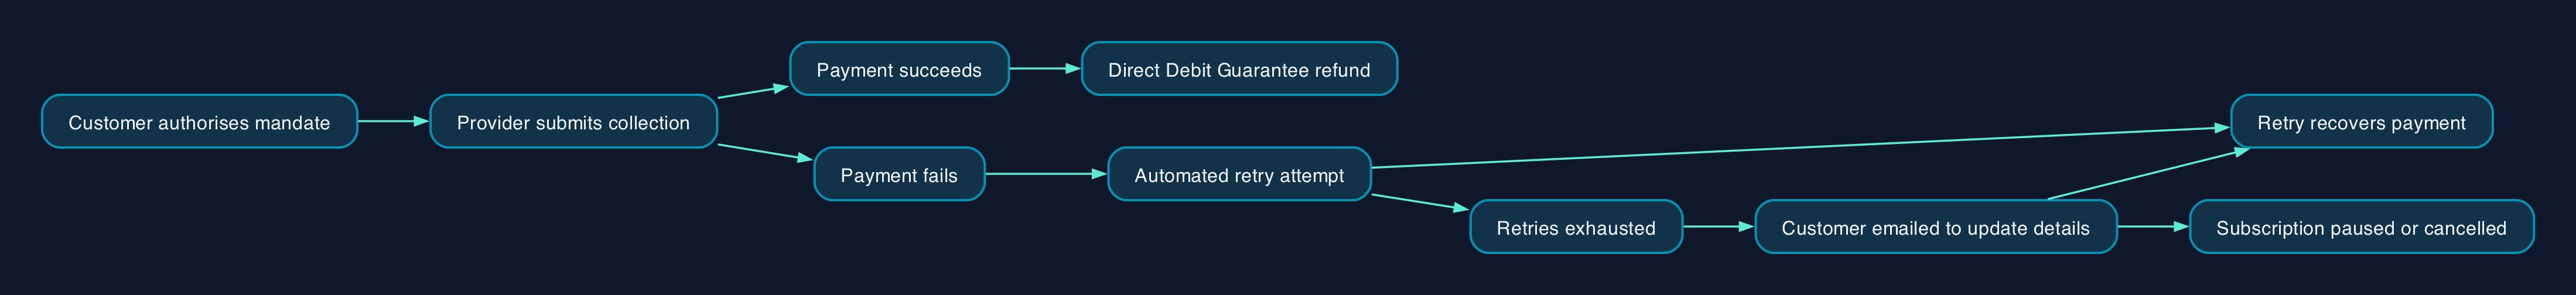
- GoCardless's own data puts average Bacs Direct Debit failures at 2.9%, against a card failure range it quotes as 10% to 15%, because bank details rarely expire or get declined the way cards do.
- Direct Debit recovery is largely automatic: GoCardless's Success+ retries recover up to 70% of failed payments on paid tiers, without needing a customer to update anything.
- Card recovery depends on the customer acting: Stripe and Chargebee both retry automatically, but a card that has genuinely expired still needs the customer to enter new details.
- Direct Debit collections take longer to reach your account (typically two to three working days once a mandate exists) and carry the Direct Debit Guarantee, which lets a bank refund a payer immediately and reclaim the money from you.
- Chargebee's Flow plan is priced and billed in US dollars, so a UK business needs to budget for exchange-rate movement on top of the percentage fee.
What Recurring Billing Actually Costs You
Recurring billing is not one decision but two, layered on top of each other. The first is the payment rail: how money actually moves from the customer's bank or card into yours, which is what GoCardless and Stripe's card processing handle. The second is the billing logic sitting above it: generating invoices, retrying failures, sending dunning emails, handling upgrades and cancellations, which is what Stripe Billing and Chargebee provide.
Stripe blends both roles into a single product: you can take payments and manage subscriptions through Stripe alone. GoCardless is a payment rail only, specialising in Direct Debit; it has no built-in subscription-management layer beyond scheduling recurring collections, though it plugs into billing platforms including Chargebee. Chargebee is billing logic only, sitting on top of whichever gateway you connect, which is why its fee is additive rather than a replacement for processing costs.
For a founder running a monthly subscription box, membership site or small SaaS product, the practical question is usually simpler: does your customer expect the frictionless one-click card checkout, or are they a business or committed subscriber who will tolerate a short Direct Debit mandate setup in exchange for a lower long-run fee. Consumer subscription boxes with impulse sign-ups tend to favour card checkout even at a higher fee, because Direct Debit mandate authorisation adds a step most shoppers will not complete on a whim. B2B memberships, trade subscriptions and higher-value coaching or software plans, where the customer already expects an invoice-like relationship, tend to favour Direct Debit because the £4 cap saves real money every month.
Pricing and Cost Model
All three providers publish transaction-based pricing with no long-term contract at entry level. Figures below are the providers' own published pay-as-you-go rates, checked live on 29 September 2026, and exclude VAT, which is added on top of GoCardless's fees under an HMRC ruling in force since April 2020.
| Provider | Core rate | Fee on a £30 monthly charge | Fee on a £1,000 monthly charge | Extra costs |
|---|---|---|---|---|
| GoCardless Standard | 1% + 20p, capped at £4 | £0.50 | £4.00 (capped) | £50/month for custom bank-statement branding, £150/month for a custom checkout (both optional) |
| Stripe Billing (pay-as-you-go) + Stripe cards | 1.5% + 20p (UK cards) plus 0.7% Billing fee | £0.86 | £22.20 | 2.5% + 20p for EU-issued cards; currency conversion and instant-payout fees are separate |
| Chargebee Flow + a card gateway such as Stripe | 0.80% Chargebee fee (or 0.65% + $99/month commit) on top of the gateway's own rate | £0.89 (using Stripe as the example gateway) | £23.20 | Flow is priced and billed in US dollars; the $99/month commit option only pays off above roughly $66,000 of monthly billing |
The GoCardless cap is the single most important number in this table for a subscription business with a mixed customer base. At £30 a month, the three providers are within pennies of each other. At £1,000 a month, GoCardless's £4 cap is roughly a fifth of what Stripe or Chargebee-plus-Stripe would charge, because their percentage fees keep scaling with the amount collected. If your average subscription is under about £20, the gap barely matters; if you sell higher-value memberships, coaching retainers or B2B software seats, it compounds fast across a customer base.
Failed Payment Recovery Compared
This is the part of the decision that actually protects revenue, because a subscription business does not lose most of its money to fraud or disputes. It loses it to payments that simply fail and are never retried successfully, known as involuntary churn.
GoCardless starts from a structurally lower failure rate because Direct Debit pulls from a bank account rather than a card. Bank details do not expire the way a card's expiry date does, and a bank account is far less likely to be replaced than a lost or stolen card. GoCardless's own published data, drawn from 55,000 customers and 52 million transactions, puts the average Bacs Direct Debit failure rate at 2.9%, against a card failure range it quotes as 10% to 15%. Its Success+ product, available on the Advanced and Pro plans, then automatically retries failed collections on the day machine learning judges most likely to succeed, recovering up to 70% of those failures on average and pushing GoCardless's overall payment success rate to 99.1%.
Stripe does not publish one comparable blanket recovery percentage. Instead it points to aggregate outcomes: businesses using Smart Retries and its wider revenue-recovery toolkit earn, on Stripe's figures, $9 in revenue for every $1 spent on Billing, and food-delivery customer Deliveroo recovered more than £100 million in a single year using Smart Retries alongside Stripe's card account updater and fraud tools. Individual customer results vary a great deal by card mix. News app SmartNews, cited by Stripe as a case study rather than a typical result, recovers 69.6% of failed payments with Smart Retries, in the same range as GoCardless's headline figure, but that comparison is not apples to apples: card failures include a mix of expired cards (which no retry timing can fix on its own) and temporary declines (which retries handle well), so the achievable recovery rate depends heavily on your customers' card types and how often they update expired details.
Chargebee sits above whichever gateway you connect, so its own Smart Dunning layer adds retry-cadence intelligence and reason-code awareness on top of that gateway's native recovery tools, rather than replacing them. Chargebee cites a case study in which subscription service Zenchef recovered 60% of unpaid accounts using its dunning system, again a single customer result rather than a published average across its user base.
The practical takeaway is that Direct Debit needs less recovery machinery to begin with because fewer payments fail in the first place, while card billing needs stronger dunning because failures are more common and more varied in cause. A subscription business that expects a lot of card churn, particularly one billing internationally or with a younger customer base more likely to switch cards, should weight Stripe's or Chargebee's dunning tooling more heavily. A business billing UK customers who are used to paying by bank transfer or Direct Debit for memberships, gym subscriptions or utilities has less to recover in the first place.
Vendor and Option Comparison
| Criteria | GoCardless | Stripe Billing | Chargebee |
|---|---|---|---|
| What it actually is | Direct Debit and Instant Bank Pay payment rail | Combined payment processor and subscription-billing engine | Subscription-billing engine only, needs a separate gateway |
| Core UK fee | 1% to 1.4% + 20p, capped £4 to £5.60 by tier | 1.5% + 20p (cards) plus 0.7% Billing fee | 0.80% (or 0.65% + $99/month) on top of gateway fees |
| Settlement speed | 2 to 3 working days once a mandate exists; first payment can take up to a week | Typically 2 working days for card payments | Depends entirely on the underlying gateway chosen |
| Failure rate starting point | Around 2.9% average (GoCardless's own data) | Cards generally fail more often; no single published UK average | Inherits whatever the connected gateway reports |
| Recovery approach | Automated retries (Success+) with no customer action required for most failures | Automated retries plus customer-facing dunning emails and card-update prompts | Adds dunning intelligence on top of the gateway's own retries |
| Minimum term | None on Standard/Advanced/Pro | None on pay-as-you-go | None listed on Flow |
| Best suited to | B2B, higher-ARPU memberships, or any business where customers already expect Direct Debit | Consumer subscriptions wanting instant card checkout and an all-in-one processor plus biller | Businesses with complex billing logic (trials, proration, multiple products) that already run a separate gateway |
| Not a good fit for | Impulse sign-ups expecting instant card checkout, or anyone needing card payments as the primary method | High-ticket monthly charges where the 0.7% fee stacks meaningfully on top of card processing | A simple single-plan subscription box that does not need proration, multi-currency or multi-entity billing |
None of the three is a universal winner. GoCardless wins on raw cost for anything above a modest ticket size and on the lower baseline failure rate that comes from bank pulls rather than card authorisation. Stripe wins on checkout speed and on being a single integration for both payment and billing. Chargebee wins when your billing logic (proration, trials, multiple products, revenue recognition) is genuinely complex enough that a dedicated billing layer earns its keep on top of whatever gateway you already use.
Editorial analysis
The GoCardless cap looks like the obvious answer for anyone billing more than about £20 a month, and for a large share of UK subscription and membership businesses it is. But the comparison is not only about fees. Direct Debit asks a new customer to hand over bank details and wait through a mandate-setup process rather than tapping in a card number, which is real friction at the point of sale for a consumer subscription box competing on impulse purchase. It also means the first payment can take the better part of a week to clear, a cash-flow consideration if you are relying on early revenue.
The safer framing for a founder weighing this decision is to separate acquisition from retention. If most of the friction and churn risk sits at sign-up, a card-first flow through Stripe protects conversion even at a higher long-run fee. If most of the risk sits in ongoing billing, once a customer has already committed, GoCardless's lower failure rate and lower fee do more work over the life of the subscription. Several UK subscription and membership businesses run both: card billing for the first payment to protect conversion, with an option to switch to Direct Debit after the trial period, when a customer has proven they intend to stay.
Chargebee's case is narrower. It is worth the extra 0.80% only once your billing logic has genuinely outgrown what Stripe Billing or GoCardless can do natively, such as usage-based pricing, multiple products with different billing cycles, or revenue-recognition reporting for a finance team. A subscription box or single-tier membership site rarely needs that yet, and paying an additional percentage fee for tools you will not use is money left on the table.
Sources
- GoCardless pricing - GoCardless
- Success+ - GoCardless
- Why some Direct Debit payments fail, and what to do next - GoCardless
- Reduce failed payments - GoCardless
- Advance payment notice, are you doing it right - GoCardless
- Bacs FAQs - Bacs (Pay.UK)
- GoCardless pricing and fees - GoCardless Support
- Stripe Billing pricing - Stripe
- How we built it, Smart Retries - Stripe
- SmartNews converts 90% of subscribers at checkout with Stripe - Stripe
- Chargebee pricing - Chargebee
- Recover more revenue, faster with smart dunning management - Chargebee
- SaaS and subscription payment processing UK - CompareCardFees.co.uk
- VAT Notice 701/49, finance - HMRC