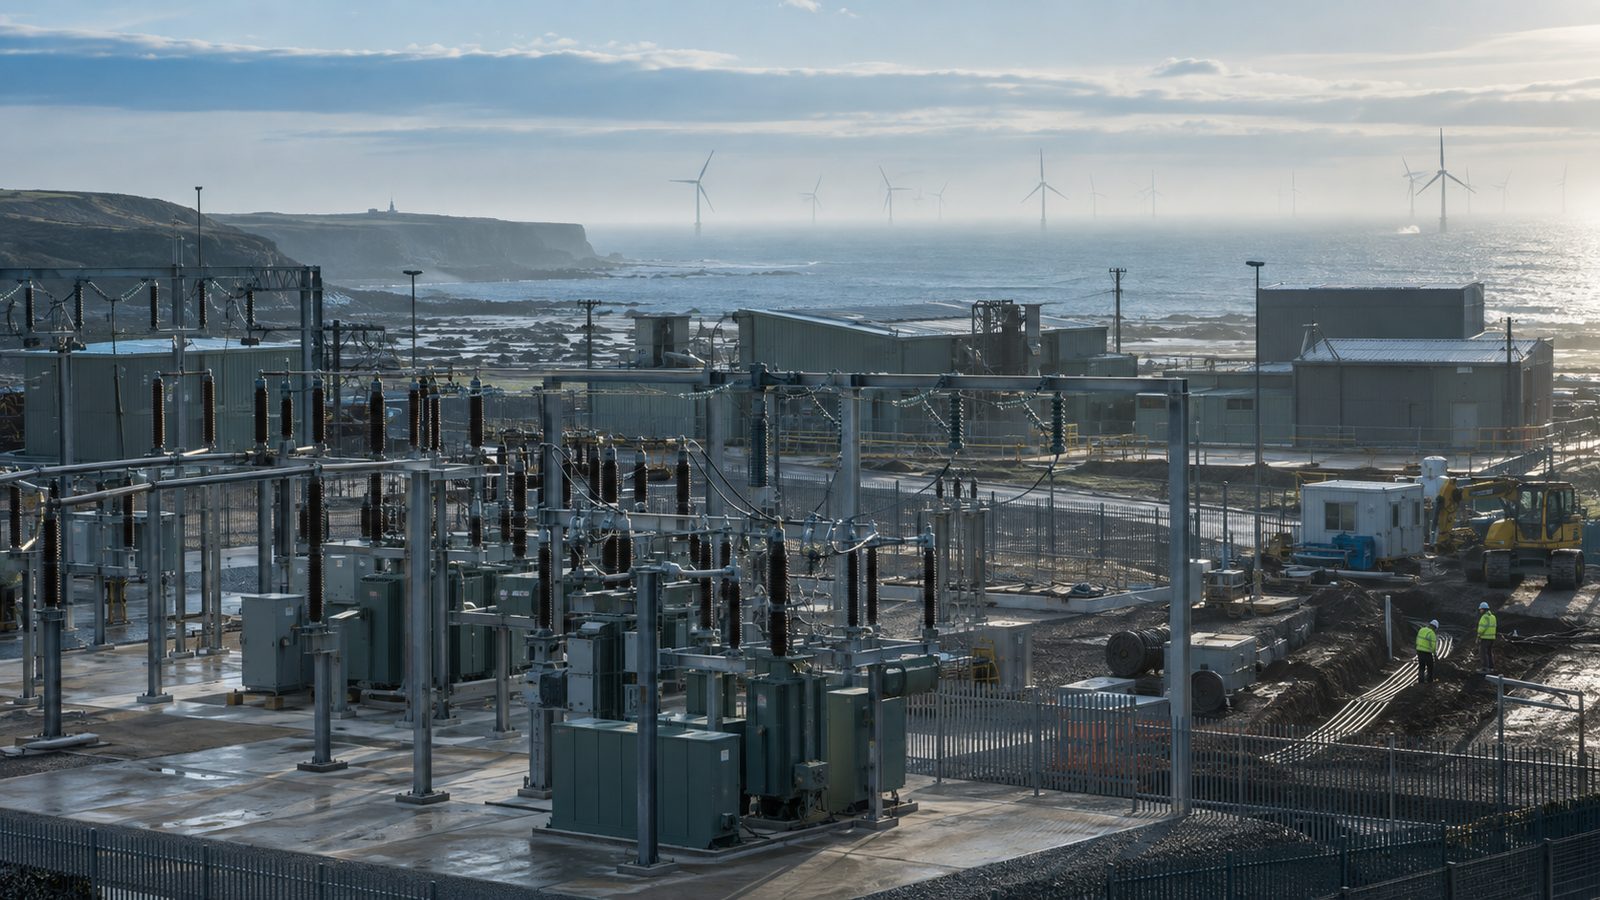
Scotland, Cumbria and North East England could attract more data centre investment if developers can turn regional energy advantages into dependable power, competitive operating costs and usable connectivity. Scotland’s digital infrastructure strategy connects renewable energy with data centre growth, while government proposals seek faster connections for strategic demand. For smaller businesses, the opportunity is potentially greater hosting choice. The deciding factors remain completed facilities, suitable services and contractual prices.
Why the regional investment case starts with electricity
A data centre investment needs a credible answer to two separate questions. How much will electricity cost, and when can the site receive the supply it needs?
The regional argument concerns the relationship between electricity generation and the network’s ability to transport it. Baker McKenzie’s January 2026 analysis of AI Growth Zone policy describes targeted electricity discounts where locating demand could reduce grid constraints. For a 500-megawatt data centre, it reports policy examples of £24 per megawatt-hour in Scotland, £16 in Cumbria and £14 in North East England.
These are reported policy examples for qualifying developments, not regional electricity tariffs available to every business. The supplied evidence does not establish final eligibility, implementation or whether a hosting provider would pass any saving to customers.
Nevertheless, the investment mechanism is understandable. If a qualifying site can secure lower electricity costs without losing reliability or connectivity, its operating economics could improve. That is a reason to investigate a location, rather than sufficient evidence to finance a building.
Scotland has an explicit infrastructure strategy
Scotland’s 2021 vision and action plan treats renewable energy and fibre connectivity as parts of the same investment proposition. It calls for resilient energy infrastructure, multiple terrestrial fibre providers and additional international subsea routes.
The distinction between ambition and delivery matters. The document supports Scotland’s strategic case, but it does not prove that a particular plot has available power, multiple carriers or a completed international connection.
Cumbria and North East England need site-level evidence
The reported energy incentive gives investors a reason to examine Cumbria and North East England. It does not establish that either region offers a uniform advantage across all sites.
For Cumbria, the supplied material is stronger on the policy rationale than on individual deliverable projects. Buyers should therefore resist treating the region’s inclusion in an incentive discussion as evidence of a new hosting service.
For North East England, the same discipline applies. A developer must connect the regional proposition to an actual site, funded infrastructure and a credible opening schedule. Regional enthusiasm cannot substitute for those documents.

Grid reform could help credible projects progress
The scale of the demand queue explains why government attention matters. Ofgem’s published total rose from 41 GW in November 2024 to 125 GW in June 2025, but the regulator warned that some projects might never proceed. Those totals describe contracted demand offers, rather than completed facilities or measured electricity consumption. Ofgem demand connections update
The Department for Energy Security and Net Zero’s March 2026 strategic demand consultation addressed speculation and prioritisation of future capacity, including for data centres. Ofgem followed with July proposals requiring stronger evidence of financial capability, commercial maturity and procurement progress. Ofgem consultation announcement
The potential benefit is a queue that gives more credible projects room to advance. It would be premature to translate that into a promised opening date for any northern facility.
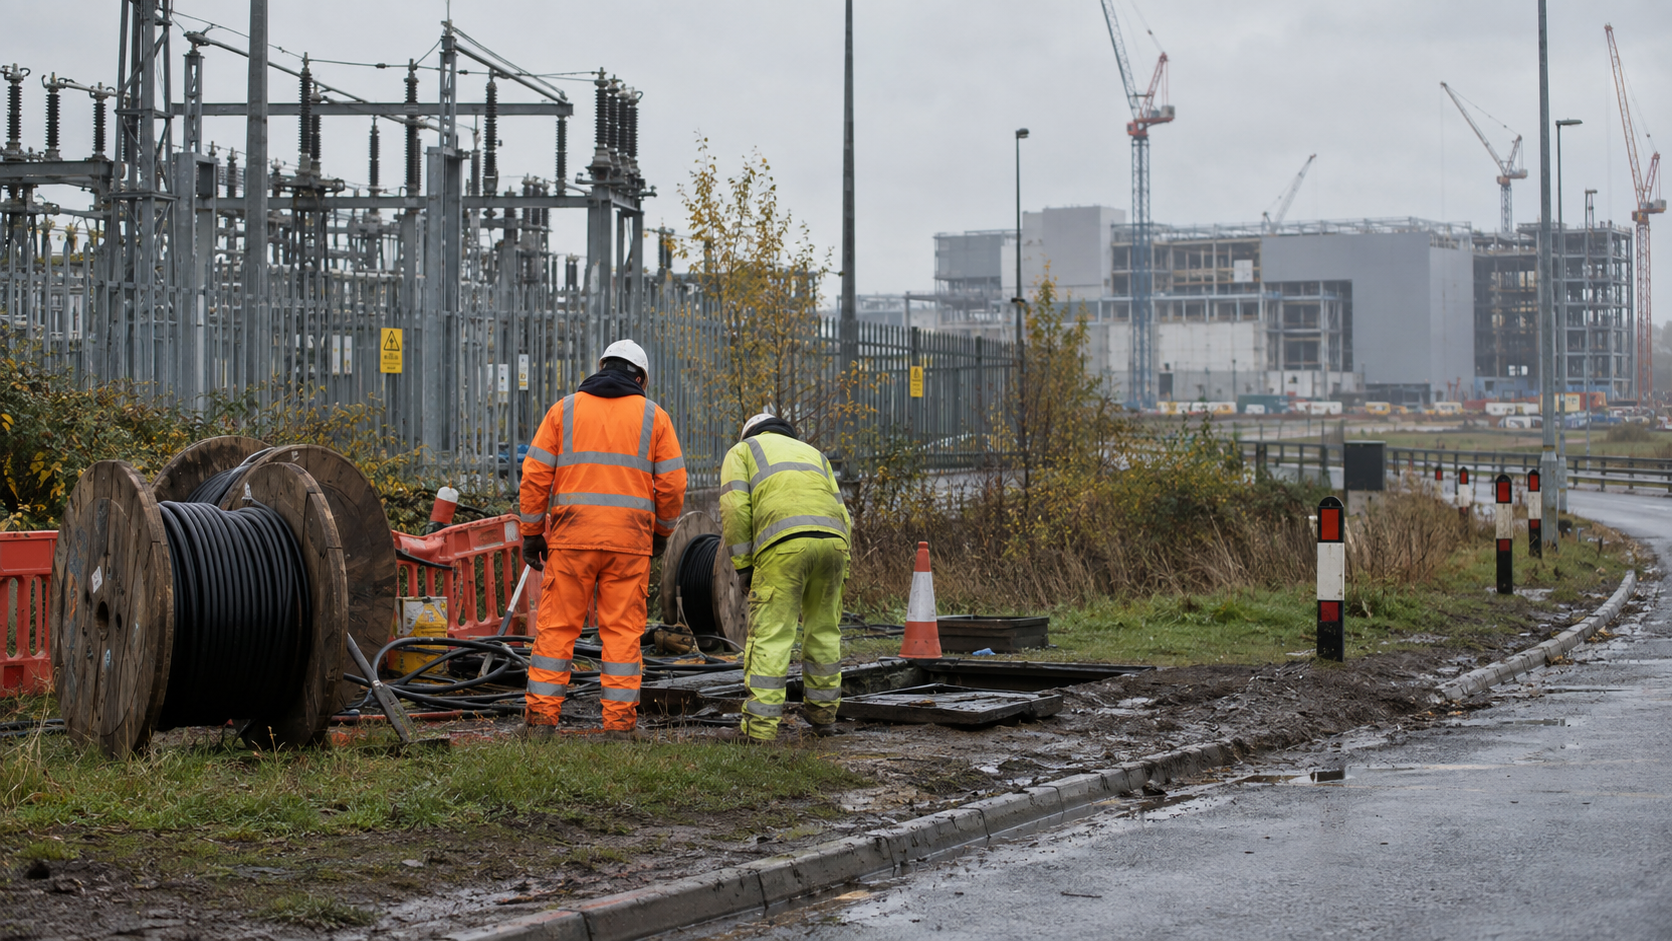
NESO also makes a physical limitation clear. Reordering applications does not build the lines, cables and other infrastructure required to supply them. Its December 2025 announcement explicitly describes connection reform as only part of the solution.
How a regional facility becomes a usable business service
For a small or mid-sized business, a data centre matters when it supports a service the organisation can buy and operate. The building, electricity supply, network connections and customer support may involve different organisations.
The following is an illustrative responsibility map for evaluating a proposed service.
| Layer | Responsibility to establish | Evidence to request |
|---|---|---|
| Electricity connection | Developer and relevant network company | Contracted capacity, delivery milestones and dependencies |
| Facility operation | Data centre operator | Commissioning status, cooling provision, backup arrangements and maintenance responsibilities |
| Connectivity | Operator and communications providers | Available carriers, route diversity and measured performance to your users |
| Hosting service | Colocation, cloud or managed service supplier | Orderable capacity, service scope, escalation process and contractual availability |
| Business recovery | Your organisation and contracted support providers | Tested backups, recovery ownership and an exit procedure |
Scotland’s strategy supports considering energy and connectivity together. NESO’s account of the remaining network construction supports checking delivery dependencies. Neither source establishes the readiness of an individual supplier. Scottish Government action plan · NESO reform announcement
For procurement, the useful question is therefore specific. Can this provider deliver the required service, at this site, by the date your business needs it?
What the investment could mean for hosting costs
A regional energy advantage could reduce an operator’s costs. Whether it reduces a customer’s invoice depends on the service and its commercial terms.
Published provider material illustrates why comparisons need care. Fast2Host’s colocation guide describes packages whose final cost varies with rack footprint, power allocation and bandwidth. A provider’s guide describes both inclusive-power packages and arrangements with separately charged electricity.
These are examples of charging approaches, not comparable quotations or evidence of northern regional discounts.
A useful total-cost comparison should cover the proposed contract period and include:
- Rack space, reserved power, electricity charging and cooling inclusions.
- Bandwidth, private connections, installation and excess usage.
- Hardware transport, migration work, testing and overlapping contracts.
- On-site engineering support, internal staff time and replacement equipment.
- Price reviews, minimum commitments, VAT treatment and exit charges.
Ask the supplier to separate fixed charges from usage charges. If its sales case depends on an energy incentive, ask where that benefit appears in the contract and what happens if eligibility changes.
Compare the service available to you
Large investment announcements and small-business hosting packages serve different buying decisions.
ConstructionIntel reports a North Lanarkshire development involving DataVita and CoreWeave. That establishes a reported investment project, not a verified catalogue of services available to smaller businesses.
By contrast, published provider material describes rack-space packages and colocation pricing structures and support considerations. Those pages give buyers more detail about procuring space for equipment, but neither establishes the availability or price of a service in the three regions discussed here.
These suppliers should not be ranked as interchangeable alternatives. An AI infrastructure project, a colocation package and a managed application service answer different needs. Start with the workload and support requirement, then compare suppliers that can actually meet it.
For a business whose current hosting works reliably, retaining it while monitoring new regional capacity is a credible option. Investment news alone is not a migration case.
Editorial analysis
The strongest argument for additional investment is the possibility of aligning electricity demand with suitable energy infrastructure while improving access to connections. Scotland adds an explicit strategy linking that ambition to fibre connectivity.
The weakest argument is that a northern location automatically means cheap, available or environmentally preferable computing. Each claim needs evidence from the proposed facility and the service contract.
Our judgement is that small and mid-sized businesses should treat regional development as a reason to expand future shortlists. Move workloads when a supplier demonstrates a measurable benefit in cost, service, resilience or support, with migration and exit costs included.
Sources
- Scottish Government — Green datacentres and digital connectivity vision and action plan for Scotland, 17 March 2021
- Baker McKenzie — United Kingdom Government Policy Paper on Delivering AI Growth Zones, 9 January 2026
- Ofgem — Demand connections update, letter dated 6 November 2025
- DESNZ — Accelerating electricity network connections for strategic demand, March 2026 consultation
- Ofgem — Tackling speculative data centre projects, 29 July 2026
- NESO — Electricity grid connection reforms to unlock investment, 8 December 2025
- Fast2Host — UK Colocation Pricing Guide 2026
- Vinters Connect — How much does Data Centre Colocation cost in the UK?
- ConstructionIntel — North Lanarkshire data centre investment report, 3 February 2026