Expect to review your invoicing process, but do not replace your accounting software solely because of the announced UK mandate. The government has said mandatory e-invoicing will cover all VAT invoices from 2029, with an implementation roadmap planned for Budget 2026. Your buying decision should turn on support for your exact software edition, trading partners and approval workflow, rather than a general promise of readiness. Government consultation response.
What changes for a UK finance team
The first decision is whether your existing system can support the required invoice exchange, not whether its invoice template looks digital. The government describes e-invoicing as the direct exchange of information between buyers’ and suppliers’ financial systems. An emailed PDF alone does not demonstrate that capability. Government consultation response.
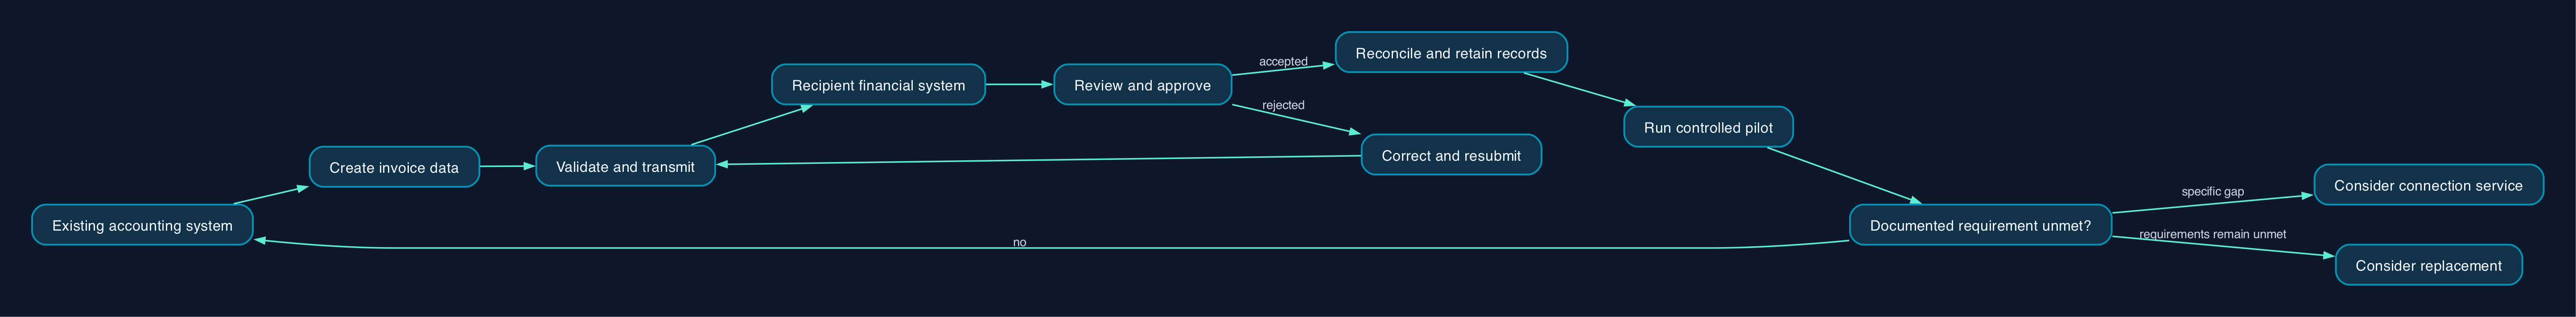
For buying purposes, separate three questions. Can your software create the necessary invoice data? Can it deliver that data to the intended customer? Can your team handle acceptance, rejection, correction and payment without losing control of the accounting record?
Our recommendation is to retain a working accounting platform while you establish those answers. Consider an upgrade, connection service or replacement only when a documented requirement cannot be met satisfactorily within the existing setup.
The evidence supplied for this article contains useful Xero and Sage material, but no direct QuickBooks or FreeAgent documentation and no final UK implementation specification. It therefore supports preparation and supplier questions, rather than a four-vendor readiness ranking or a claim that any product meets the eventual rules.
UK requirements and their limits
The strongest policy evidence here is the government’s consultation response, updated on 26 November 2025. It announces mandatory e-invoicing for all VAT invoices from 2029 and says an implementation roadmap will be published at Budget 2026. Treat that as the announced direction; the supplied extract does not settle exemptions, technical formats, penalties or the precise commencement date. Government consultation response.
Public-sector invoicing has a separate legal context. Government guidance on the Procurement Act 2023 explains that section 67 implies a requirement for contracting authorities to accept and process undisputed invoices in the required electronic form for contracts within its scope. That is an acceptance obligation on the authority, not evidence that every supplier must already replace its accounting package. Government guidance on electronic invoicing and payment.
If you supply a public body, establish which procurement regime and contractual requirements apply to that particular contract. Keep that assessment separate from preparation for the announced VAT-invoice mandate.
This is not legal advice; consult your legal counsel.
How the invoice workflow should work
Use a pilot to establish responsibilities from invoice creation to reconciliation. The following is a proposed operating model for a small or mid-sized business, rather than a claim that all four suppliers provide identical functionality.
| Stage | Proposed owner | Evidence to require before acceptance |
|---|---|---|
| Create the invoice | Finance team | Correct customer, tax treatment, line items and purchase-order references |
| Validate and transmit | Software supplier or connection provider | Supported format, recipient eligibility and a recorded transmission result |
| Review incoming invoices | Accounts payable or bookkeeper | Invoice reaches the intended review queue without creating duplicate bills |
| Resolve exceptions | Named finance owner, supported by the supplier | A rejected invoice can be identified, corrected and resubmitted with a traceable history |
| Approve payment | Authorised manager | Existing approval controls still operate |
| Reconcile and retain records | Finance team or accountant | Invoice, credit note, payment and status records remain accessible and exportable |
Xero provides a concrete example of why receiving and approving should remain separate: its product page says incoming eInvoices become draft bills for review. Its sending instructions also distinguish users who can approve and send from those who must submit a draft for approval. Xero’s receiving workflow and sending permissions.
Ask whoever configures the service to demonstrate a failure as well as a successful transmission. A useful handover shows the finance team where an error appears, who owns it and how to prevent a second invoice being issued accidentally.
Pricing and the full cost of preparation
Do not compare a complete accounting subscription with an e-invoicing connection fee as though they buy the same thing. Request separate figures for the platform, any additional service and the work needed to make the process usable.
The supplied Xero UK page lists the following monthly prices after its introductory offers. These are accounting-plan reference prices from the evidence snapshot dated 28 September 2026, not prices for e-invoicing alone. Xero’s listed UK plans.
| Xero UK plan | Listed monthly price after the introductory offer | Pricing qualification |
|---|---|---|
| Ignite | £18 | Accounting subscription, not an e-invoicing implementation quotation |
| Grow | £39 | Accounting subscription, not an e-invoicing implementation quotation |
| Comprehensive | £55 | Accounting subscription, not an e-invoicing implementation quotation |
| Ultimate | £70 | Accounting subscription, not an e-invoicing implementation quotation |
The supplied extract does not establish VAT treatment, minimum purchase quantity or contractual commitment for these headline subscription figures. Confirm those terms before budgeting. The prices exclude any separately commissioned configuration, training or migration work from this comparison; they are not a complete cost forecast.
Xero also advertises free registration for e-invoicing. That is a useful distinction from the accounting-plan charge, but it does not establish that every workflow, connection or support requirement will be included. Xero’s registration statement.
For Sage, QuickBooks and FreeAgent, no comparable e-invoicing price schedule is established by the supplied material. A blank price is an unanswered procurement question, not a zero-cost service.
| Cost component | What to put in the supplier’s quotation request |
|---|---|
| Existing accounting subscription | Identify any required edition change and its incremental cost |
| E-invoicing service | Separate registration, recurring charges, usage limits and overage rates |
| Configuration and connections | Price each accounting system, company and trading-partner requirement |
| Data preparation | Specify responsibility for correcting customer and supplier records |
| Testing and training | Include exception handling, permissions and finance-team handover |
| Support and operation | Define service hours, escalation, maintenance and retained staff work |
| Exit | Price data export, connection removal, record access and transition support |
For a total-cost comparison, use the same evaluation period for every option. Include internal staff time and existing costs that continue, while avoiding double counting anything already bundled into the subscription. Leave the total conditional until the missing charges and delivery scope are known.
Migration and rollout checklist
These are recommended acceptance checks, not a declaration that a migration is necessary.
- [ ] Record the exact product and edition. Include the country version, connected applications and any partner-managed components.
- [ ] Map invoice routes. Document how sales invoices, supplier bills and credit notes currently enter and leave the business.
- [ ] Identify recipient requirements. Obtain the required format, destination and references from each pilot trading partner.
- [ ] Get a written supplier response. Confirm supported invoice flows, prerequisites, charges, limitations and the product roadmap relevant to your edition.
- [ ] Preserve records before changes. Take the available backup or export and establish how staff will access historic invoices.
- [ ] Assign permissions and responsibilities. Name who can configure, send, approve, correct and escalate.
- [ ] Run a controlled pilot. Reconcile the transmitted invoice with the accounting entry and the recipient’s acknowledgement.
- [ ] Test exceptions. Demonstrate rejection, correction, credit notes and duplicate prevention for the workflows you actually use.
- [ ] Train the finance team. Require staff to complete the normal process and an exception without the implementer operating it for them.
- [ ] Agree rollback and acceptance. Before disabling an existing route, document the permitted fallback and obtain finance-owner approval of the pilot results.
Avoid changing accounting defaults merely to experiment with invoice exchange. For example, Sage 200 Standard’s documentation says the VAT-inclusive or VAT-exclusive pricing choice cannot be changed after saving an invoice, sales order, pro forma or quotation. That is a reason to involve the person responsible for the existing configuration before altering it. Sage 200 invoicing setup.
Comparing Xero, Sage, QuickBooks and FreeAgent
Compare the exact product you use against a written requirement. A supplier’s general e-invoicing statement cannot replace confirmation of edition, territory, recipient coverage and operational support.
| Supplier | What the supplied evidence establishes | What remains to confirm | Buying implication |
|---|---|---|---|
| Xero | Its UK page describes direct invoice exchange, incoming draft bills, Peppol connectivity and VAT eligibility conditions. Product details | Your organisation’s eligibility, intended recipients, document types, support terms and eventual UK requirements | Test the existing route before considering replacement |
| Sage | Sage Network describes sending, receiving, validation, conversion and acceptance or rejection status. Service description | Exact UK product and version coverage, activation steps, partner responsibilities and charges | Obtain an edition-specific proposal before buying an upgrade or connector |
| QuickBooks | No direct product documentation was supplied | UK edition support, native or connected delivery, recipient coverage, permissions, costs and support | Request written confirmation; the evidence gap does not establish a missing feature |
| FreeAgent | No direct product documentation was supplied | UK product support, activation or connection requirements, supported workflows, costs and support | Assess the existing product against the same requirements as the other suppliers |
For usability, ask the supplier to show what the bookkeeper sees after a rejected invoice. For compatibility, test the actual customer or supplier rather than relying on a generic connection claim. For support, identify who investigates when the accounting entry exists but the recipient cannot find the invoice.
Retaining the platform is the strongest starting option when the accounting workflow works and the required exchange can be demonstrated. A connected service deserves consideration when it fills a specific, tested gap. Replacement becomes credible when documented requirements remain unmet, or when wider accounting problems already justify the disruption.
None of those routes should be selected on an unsupported promise that it will automatically satisfy every future UK requirement.
Editorial analysis
The useful purchase is a working invoice process with clear ownership. For an existing customer, that may mean configuration and training rather than a different accounting package.
Xero’s supplied documentation gives a clearer starting point for a practical pilot than the other evidence available here. Sage’s material describes a broader service proposition requiring product-specific confirmation. That difference reflects the evidence available for this article; it does not establish that Xero is universally the better accounting system.
Spend first on identifying gaps that a supplier can demonstrate and price. A proposal should explain what changes for your finance team, what remains manual and who resolves a failed transmission.
Sources
The article uses the supplied research extracts, with snapshot dates up to 28 September 2026. Publication or update dates are included below only where stated in the source text.
- HMRC and Department for Business and Trade — Promoting electronic invoicing across UK businesses and the public sector consultation response, updated 26 November 2025.
- UK Government — Guidance on Electronic Invoicing and Payment.
- Xero — eInvoicing Software for Direct Invoicing.
- Xero — eInvoicing and eInvoices in the UK.
- Xero Central — Send an eInvoice.
- Sage — Sage Network E-invoicing.
- Sage — Sage 200 Standard invoicing setup.